
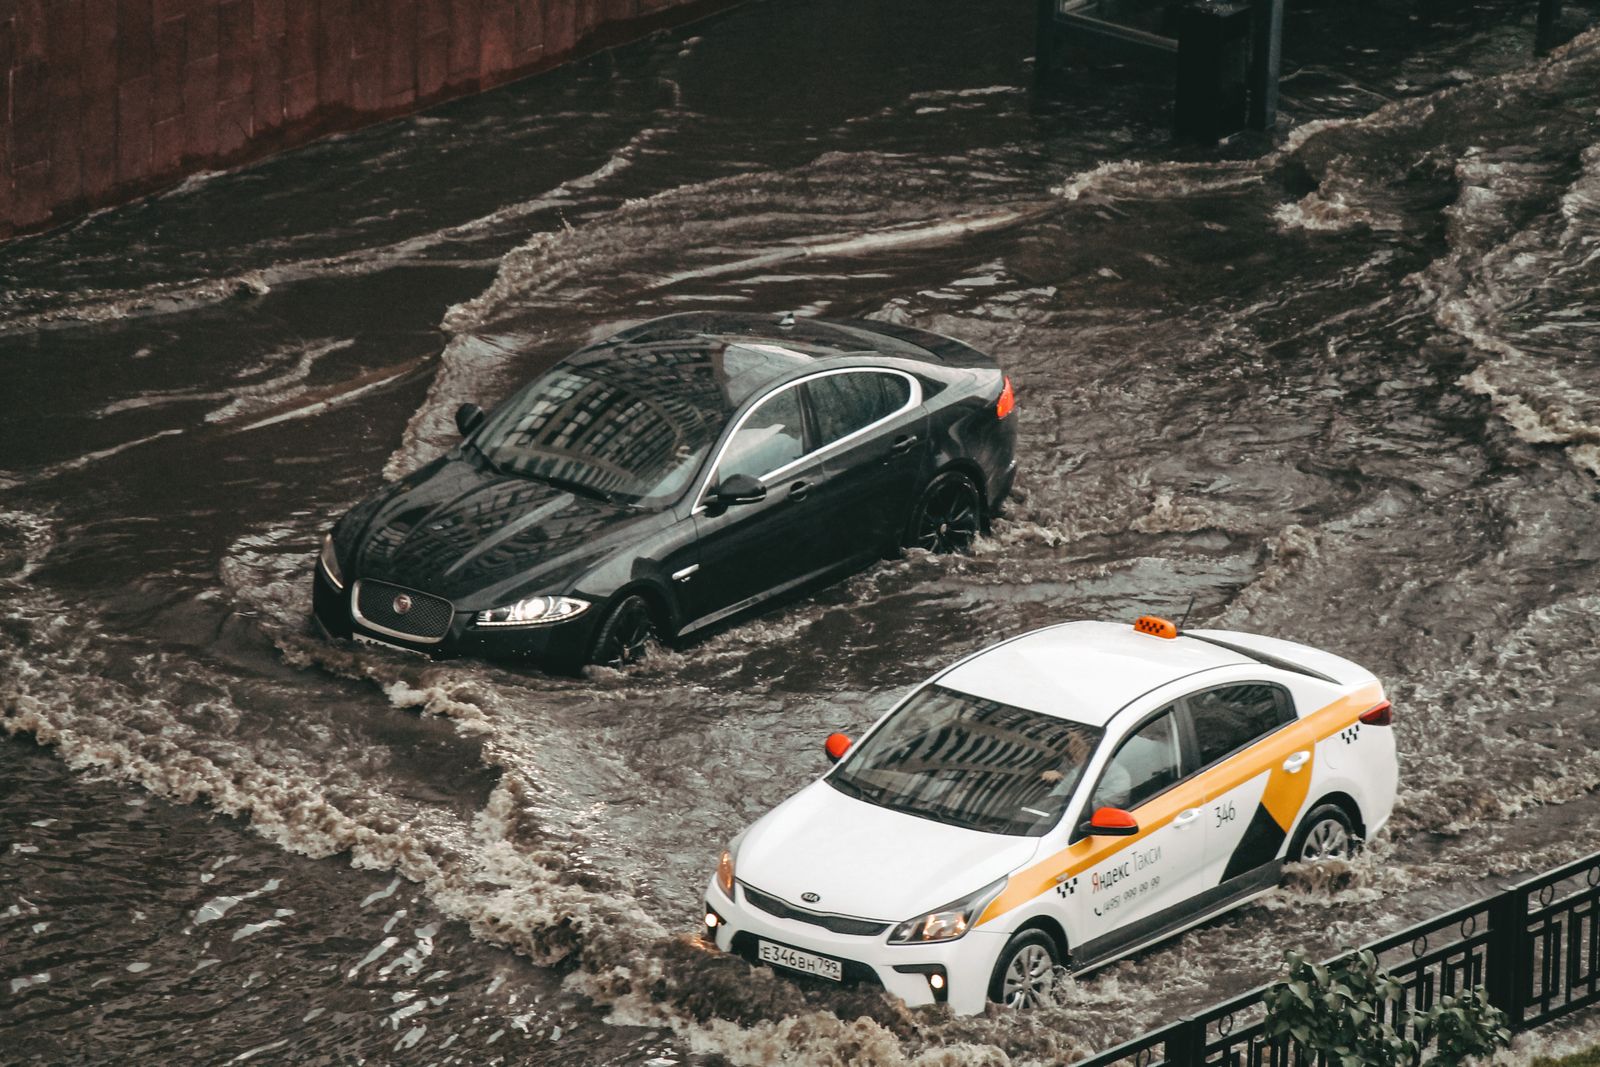
Insuring a flood-title car is often harder than buying one. Liability might be available. Comprehensive and collision are where underwriters get picky — and where a “great deal” becomes an uninsurable driveway ornament.
Late September 2026, we still see shoppers negotiate hard on a water-branded car before calling their insurance agent. We’ve watched approvals collapse after the VIN’s flood language hit the desk. NHTSA and consumer outlets keep warning that flood cars fail late; insurers know that story and price it into their appetite.
Official CARFAX and AutoCheck retail singles still get quoted around $39.99–$44.99 depending on the cart (confirm at checkout). Through our licensed reseller checkout, guest reports are about $5.50, member about $4.50, and the CARFAX+AutoCheck bundle about $6.75; credit packs often start near $3. Confirm before you pay. We resell official reports and are not affiliated with CARFAX, AutoCheck, or Experian.
Why flood brands change the insurance conversation
Look: water invades connectors, restraint modules, and body cavities in ways a weekend detail cannot prove away. Insurers price that as elevated claim risk. Some write liability-only. Some decline the VIN entirely. A few specialty markets will write with inspections and higher premiums. None of that is theoretical — ask in writing with the VIN before you travel.
Here’s the catch. “My cousin insured a rebuilt car” is not a flood quote. Rebuilt salvage and flood are adjacent headaches with different underwriting flavors. Pair this page with insuring a rebuilt title, what flood title means, and flood-title lending reality if money and coverage both have to clear.
- Call your agent with the exact VIN and brand language from a fresh PDF.
- Ask specifically about comprehensive and collision — not only liability.
- Ask whether an inspection or moisture scan is required before binding.
- Get the answer in an email or portal note you can keep with the purchase folder.
Documents that make the call faster
So bring a dated CARFAX or AutoCheck PDF, title face photos, and any auction photos if the car passed a salvage lane. Blunt risk: binding a policy on a seller’s cropped JPEG, then discovering the full file shows flood branding your agent never saw. Pull your own report. Match the VIN on the dash to the header.
Honestly, if you need a loan and insurance both, sequence the calls. Some credit unions will not fund without proof of comprehensive. Some insurers will not write comprehensive on that VIN. Finding that out after you wired a deposit is an expensive education. Related lender friction lives on credit-union flood loan policy questions once that page is current.
We’ve also seen agents ask for proof the car completed a state rebuilt process and passed inspection. That paperwork is not optional flavor — it is how they decide whether the VIN is even eligible. If the seller “lost” those docs, treat that as a walk signal unless you can rebuild the file from the DMV.
If nobody will write comprehensive
Treat that as a buy signal to walk unless you truly accept liability-only risk and cash ownership forever. A flood car you cannot comprehensively insure is a different product than a flood car with a specialty policy. Price storage, repair surprises, and near-zero refinance options into the “deal.”
Archive the declination notes with the VIN. Future you will want proof you asked. Confirm report pricing at checkout the day you pull — retail singles wander $39.99–$44.99, and reseller carts show guest/member numbers only in the cart you are actually using. Pull again if a week passes before you buy; feeds update.
If the seller rushes you past insurance questions with “as-is, everyone does it,” slow down. Coverage appetite is part of the total cost of ownership, not a paperwork afterthought you handle on Monday after the weekend wire.
One more practical habit: ask whether the insurer will renew next year on the same VIN, not only whether they will bind today. Some desks write a first term and then non-renew after a closer look. Get renewal appetite in writing when you can. If the answer is fuzzy, price that uncertainty into the purchase — a one-year policy on a flood car is not the same product as stable multi-year coverage on a clean-title daily.
If you already own the car and coverage disappeared at renewal, document every call. Some specialty markets exist, but they are not the same price as a clean-title policy at a big carrier. Price that delta into whether keeping the car still makes sense versus selling at a branded-title number.


Comments (0)
No comments yet. Be the first to share your thoughts!
Log in to leave a comment.