
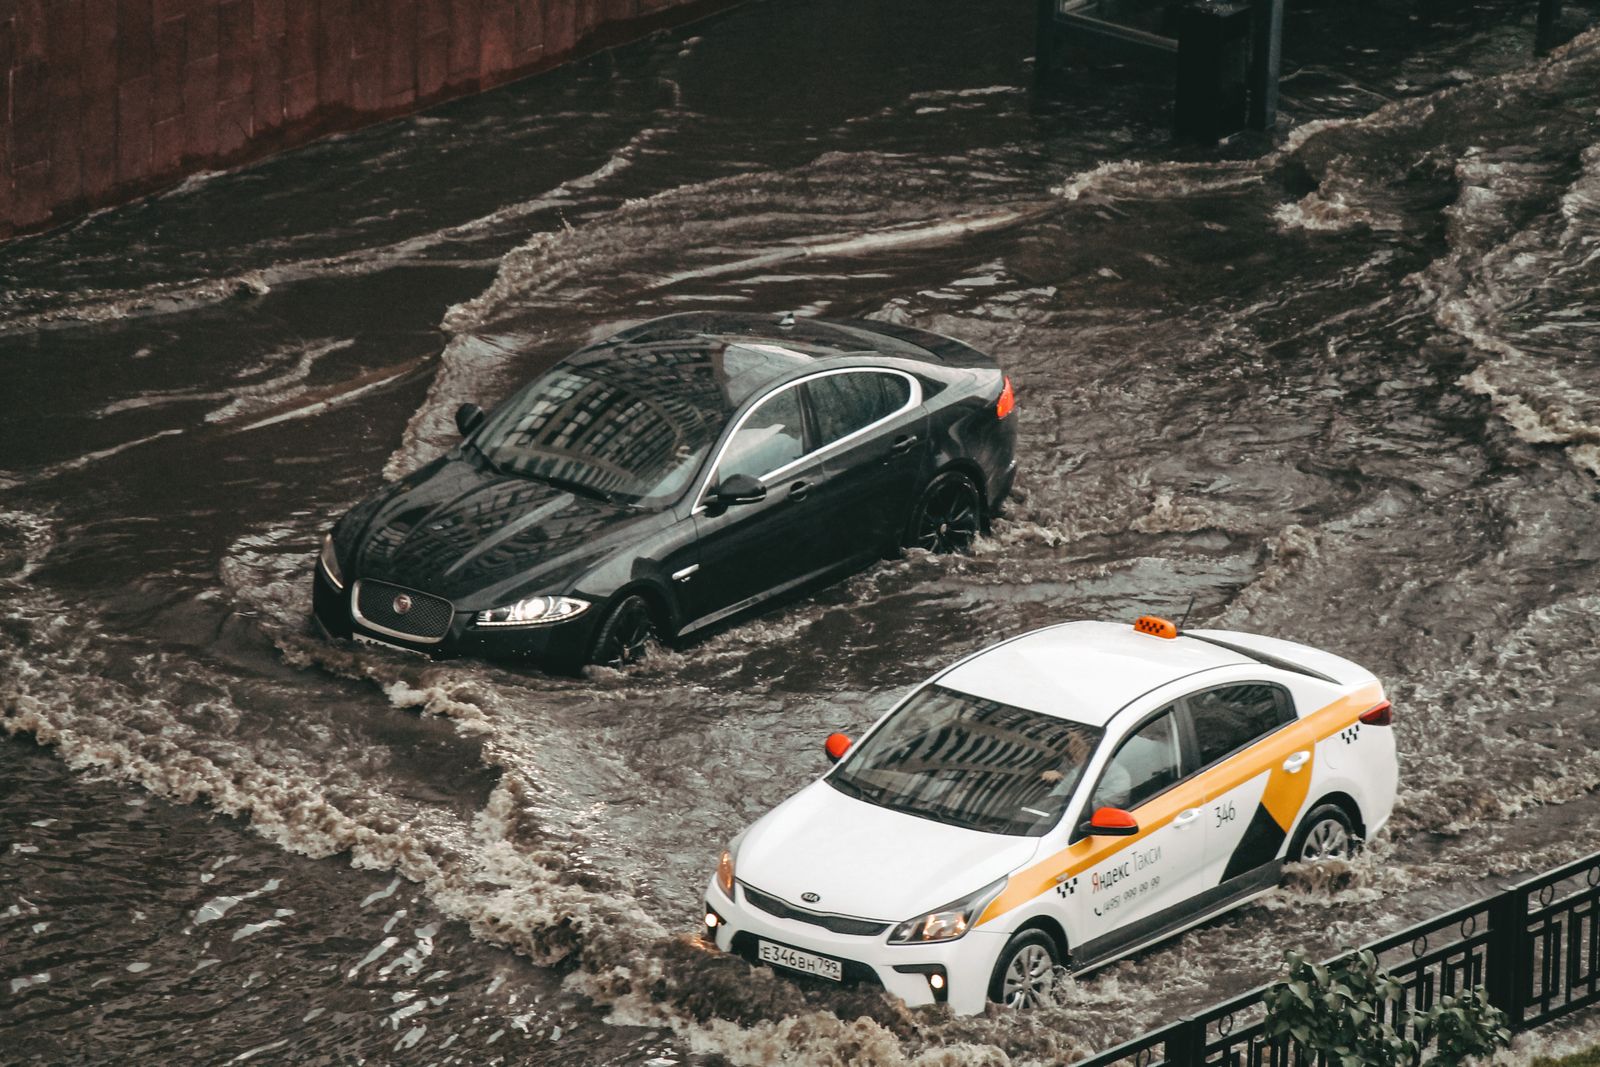
Buying a used car in New Orleans means treating flood history as a default research question — not an exotic edge case you only check after the test-drive feels fun.
Late September 2026, NOLA and river-parish listings still mix local storm survivors with imports from other disaster zones. We’ve opened reports where Louisiana branding told the truth and others where the dangerous story lived in older out-of-state rows. Parades and sunshine do not dry modules.
Late September 2026, storm-season inventory still moves across state lines months after the headlines fade. Official CARFAX and AutoCheck retail singles still get quoted around $39.99–$44.99 depending on the cart (confirm at checkout). Through our licensed reseller checkout, guest reports are about $5.50, member about $4.50, and the CARFAX+AutoCheck bundle about $6.75; credit packs often start near $3. Confirm what you see before you pay. We resell official reports and are not affiliated with CARFAX, AutoCheck, or Experian.
Why New Orleans shoppers need a flood-first checklist
Look: coastal and river metros recycle water-damaged cars into ordinary classifieds with soft language like “needs TLC†or “clean title, priced to move.†NHTSA warns that flood-damaged vehicles can present long-term electrical and safety risks. Consumer Reports and USA Today keep documenting how storm cars migrate inland and into neighboring metros. A local zip code on today’s listing does not prove the car lived a dry life. Levee, canal, and hurricane histories make water damage a regional shopping skill. Dealers and private sellers both move volume after major events.
Here’s the catch. Title brands help when states apply them, but uninsured floods and incomplete disclosure still create quiet cars. Your stack is a fresh official history report, NMVTIS-aware skepticism, a flood-focused PPI, and daylight inspection for silt, musty carpet, fogged lamps, and fresh under-carpet fasteners. Honestly, if a seller blocks any of those steps, the discount is bait. Related reading on this site includes Louisiana flood salvage guide Baton Rouge flood cars Houston flood checklist.
Pair Louisiana state salvage and flood literacy with a metro inspection that assumes humidity and intermittent electrical faults.
Step-by-step before you travel to see the car
So get the VIN in writing first. Pull CARFAX and AutoCheck the same day. Read title brands, salvage/flood notations, auction rows, and the registration timeline for hurricane and inland flood windows. If the car hopped states right after a major storm, raise your scrutiny even when the brand section looks empty. Send the PDF to your inspector before you burn a Saturday on a long drive.
- Match dash VIN, door sticker, and report header character for character.
- Reject cropped seller screenshots; buy or open a full official PDF.
- Inspect for moisture, silt, rust in odd places, and electrical gremlins.
- Ask insurance whether they will cover this VIN before you fall in love.
- Keep deposits tiny until paperwork and PPI clear.
Blunt risk: wiring money because the seller “already ran Carfax†and will not let you run a fresh pull timed to the meet-up. Feeds update. Fake PDFs exist. Your own checkout is cheaper than a surprise brand. Edmunds’ flood-avoidance guidance and KBB’s history-report primers rhyme with the same order: database, eyes, mechanic, then money.
NOLA practical buying order
Get the VIN, pull both reports, then walk the car with a moisture meter mindset even if you do not own the tool — your PPI shop should. Check spare wells, under carpets, and headlamp lenses. Ask pointed questions about garage parking versus street parking during specific storm years. Vague answers are data.
If the price is far under comps, assume you are being paid to take water risk until proven otherwise. We’ve steered buyers to slightly higher clean-history units and watched them skip months of electrical chase.
We’ve walked New Orleans shoppers through reports that looked calm until an older out-of-state flood row appeared after a refresh. Time matters. Pull again if the listing ages. Archive PDFs with dates in the filename so you are not arguing from memory later.
If financing is in play, remember flood and rebuilt brands change lender appetite fast. Call the desk with the brand spelled out before you bid. Cash does not erase physics — it only removes the bank’s veto.
Keep a simple decision rule on your phone: no VIN in chat before travel, no fresh dual report, no deal. That rule alone kills most flood-resale theater. We’ve saved more dollars with stubborn process than with clever negotiation after the fact.


Comments (0)
No comments yet. Be the first to share your thoughts!
Log in to leave a comment.